9 Things to Watch for the 2027 ACA Open Enrollment Period
The Affordable Care Act (ACA) Marketplace 2027 Open Enrollment period starts November 1, 2026, in most states. In 2026, the enhanced premium tax credits expired, provisions of the 2025 budget reconciliation law (the “One Big Beautiful Bill Act”) began to take effect, and Trump administration regulations began to change Marketplace coverage, with effects expected to carry into 2027 enrollment. Further changes in the ACA Marketplaces are again expected in 2027.
Here are the nine things to know for the 2027 Open Enrollment period:
1. Premiums are going up by double-digits, but most people get a subsidy.
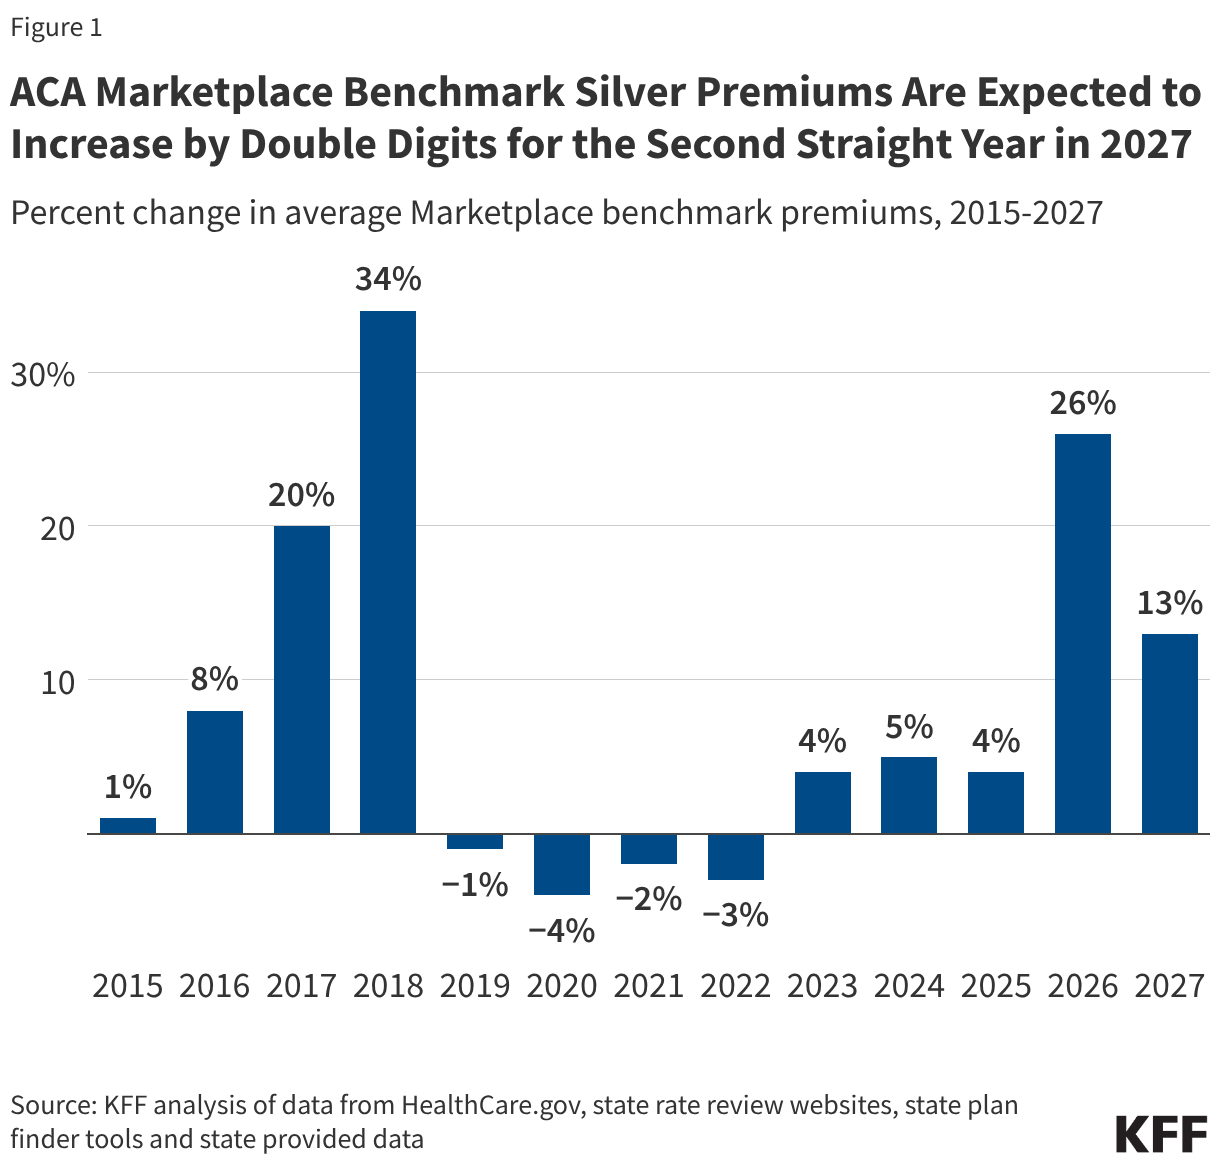
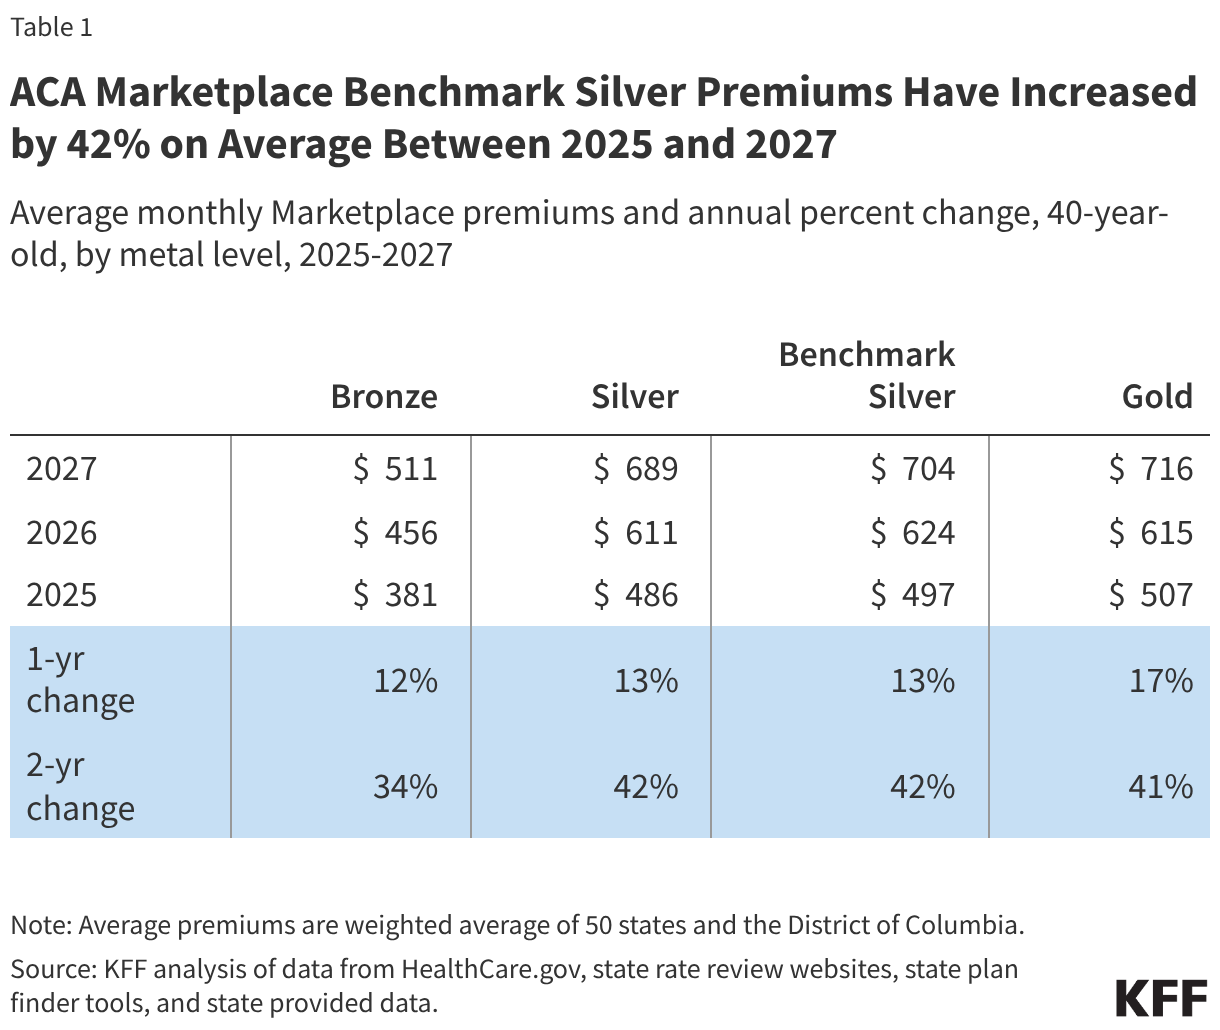
While insurers proposed a median premium increase of 15%, the average increase in finalized benchmark silver premiums for 2027 is 13%, marking a second consecutive year of double-digit proposed increases (these premiums rose by 26% from 2025 to 2026). In states that use the Healthcare.gov platform, benchmark silver premiums are increasing 11%, whereas states that run their own enrollment platforms are seeing premium increases of 16%. From 2025 to 2026, HealthCare.gov states saw a 30% increase, whereas state-based Marketplaces saw a roughly 17% increase in benchmark premiums.
In their rate filings, insurers point to a higher-than-usual increase in the underlying cost of care, which is not unique to the ACA Marketplaces; some employer plans have also seen steep cost increases.
ACA Marketplace insurers also cite the expiration of the enhanced premium tax credits and the resulting changes in the risk pool as factors contributing to higher premiums. KFF’s analysis of insurer filings found that insurers estimated risk pool changes added about four percentage points on average to premiums in 2026 and expect a similar, additional effect in 2027.
Most enrollees get a subsidy that will cushion the impact of these increases in 2027. However, people with incomes above 400% of the federal poverty level (FPL) will be particularly hard hit because they no longer qualify for premium tax credits and must pay the full cost of coverage. Sharp premium increases in 2027 follow even steeper increases going into 2026. These higher costs may lead additional healthier enrollees to drop coverage, further worsening the risk pool and putting additional upward pressure on premiums.
2. Marketplace enrollment is declining following the expiration of enhanced premium tax credits, and may continue to fall for other reasons.
Enrollment in the ACA Marketplaces declined following the expiration of the enhanced premium tax credits. During the 2026 Open Enrollment Period, Marketplace plan selections fell by 1.2 million from 2025. By February 2026, effectuated Marketplace enrollment (i.e., people who pay their premiums and remain enrolled) was down 12% (or 2.6 million people) from the previous year to 19.2 million people. More recent Marketplace-specific enrollment data are not yet available, but enrollment data for the individual market suggest the decline may have continued through the first half of 2026. Data for the broader individual market, which includes both Marketplace coverage and plans purchased directly from insurers or brokers, show a continued decline. Individual market enrollment fell 18% by June 2026, from 25.2 million to 20.5 million people—a loss of more than 4.6 million.
Looking ahead to 2027, several insurers have said they expect the market to continue to deteriorate in 2027 as a continued result of the enhanced premium tax credits ending. Some enrollees who were able to keep coverage in 2026 may no longer be able to make ends meet.
As discussed more below, anti-fraud efforts and changes to eligibility for tax credits affecting certain immigrants will also have a downward effect on Marketplace enrollment. In its latest projections, the Congressional Budget Office (CBO) estimated ACA Marketplace enrollment would fall from a peak of 22.4 million in 2025 to 13.1 million in 2027.
3. Insurer exits outnumber new entrants.
The number of insurers participating in the ACA Marketplaces is expected to decrease again in 2027, with more insurers announcing plans to exit the Marketplace than to enter. As of October 29, 2026, 11 carriers had announced plans to exit at least one state for 2027, while seven carriers had announced plans to enter a new state. Shrinking Marketplace enrollment after the expiration of the enhanced premium tax credits has reduced the potential market for insurers and raised concerns about the future of the risk pool. The changes will vary across states, but in some areas, consumers will have fewer insurers to choose from in 2027. Cigna, for example, is leaving the individual market in all 11 states where it currently participates.
Insurer exits can reduce competition and leave consumers with fewer choices of plans and provider networks and disrupt coverage for some enrollees.
4. Some state-based Exchanges have backfilled lost enhanced federal tax credits.
Some states that operate their own Exchanges are using state-funded subsidies to help offset the expiration of the enhanced premium tax credits, with several continuing or expanding assistance in 2027. New Mexico went furthest in 2026, fully backfilling the lost federal assistance for Marketplace enrollees. While enrollment declined nationally, New Mexico saw Marketplace enrollment grow during the 2026 Open Enrollment Period. The state is continuing its assistance in 2027.
Other states provided more limited assistance in 2026 and may expand eligibility in 2027. California, for example, is continuing state-funded premium subsidies but is expanding its program to partially backfill lost enhanced tax credits for households with incomes between 165% and 200% FPL. Previously, only households with incomes between 138% and 165% FPL were eligible for state assistance to replace any portion of the expired enhanced tax credits. Several other states have also maintained subsidy programs such as New Jersey, while Rhode Island and Virginia moved to create new state-specific subsidies for the 2027 plan year. These state efforts may help some consumers afford coverage despite the loss of federal assistance, but the amount of support available varies by state and income.
5. Recent federal actions to address fraud may affect enrollment counts and make it more difficult for enrollees needing brokers’ services in 2027.
Recent initiatives to combat Marketplace broker fraud could impact counts of the number of enrollees this Open Enrollment cycle, the availability of enrollment assistance, and certain agent and broker practices in 2027. Some provisions that attempt to address fraud by placing new requirements on consumers have been temporarily paused due to court action (discussed more below).
In September 2026, HHS reported they cancelled coverage for approximately 760,000 individuals who CMS says were “phantom” enrollees, meaning a broker or agent may have signed them up without their knowledge. HHS sent a list of about 1.2 million people to insurers to review. These individuals had been signed up by an agent or broker, had no premium payment and were missing a Social Security number or immigration document that could be verified in real time. If insurers were unable to make contact with these individuals or verify they had incurred claims, CMS cancelled the coverage. There are reports that some enrollees have had their coverage reinstated suggesting that the criteria CMS used to identify potential fraud may have also flagged legitimate enrollees. Others who lost coverage through these efforts may not have their coverage restored.
Additionally, HHS is implementing new safeguards on certain agents, brokers, and web-broker practices that put consumers at risk of inappropriate or fraudulent enrollments. This follows investigations of brokers and other related entities moving enrollees to different plans or enrolling them in Marketplace coverage without their knowledge. For instance, the HHS Notice of Benefit and Payment Parameters for 2027 updates standards of conduct for agents, brokers, and web-brokers regarding prohibited marketing tactics, including but not limited to providing cash, monetary rebates, or cash equivalents to persuade consumers to enroll in coverage; falsely claiming that consumers will always qualify for zero-dollar insurance or zero-dollar premiums; and providing false information on enrollment timelines and deadlines. Agents, brokers, and web-brokers must submit marketing materials to HHS upon request in response to monitoring, auditing, or enforcement activities. Agents, brokers, and web-brokers that contract with a third party or other entity to produce marketing materials must ensure that those entities follow the requirements that apply to agents, brokers, and web-brokers.
In September 2026, HHS announced an even more stringent restriction that temporarily pauses the registration of new agents and brokers in the federally facilitated Marketplace and for Marketplaces that operate on the federal platform until February 2027. CMS estimates that approximately 19,000 new agents and brokers would have registered absent the temporary restriction. Combined with the reductions in Navigator funding for 2026 announced in February 2025, consumers may have less access to enrollment assistance in 2027.
6. Some lawfully present immigrants will no longer qualify for subsidized Marketplace coverage in 2027.
Currently, subsidized ACA Marketplace coverage is available to lawfully present immigrants. Lawfully present immigrants include lawful permanent residents (LPRs or green card holders), people on work visas, and humanitarian immigrants such as refugees, victims of human trafficking, asylees, among others. Undocumented immigrants are not eligible to purchase ACA Marketplace coverage, even at full cost. While immigration statuses eligible to purchase ACA Marketplace coverage have not changed for 2027, the 2025 budget reconciliation law limits eligibility for tax credits in the Marketplace to only certain groups of lawfully present immigrants including:
- Lawful permanent residents
- Cuban and Haitian entrants, as defined in section 501(e) of the Refugee Education Assistance Act of 1980
- Any lawful residents living in the U.S. under the Compact of Free Association
Other lawfully present immigrants such as refugees, victims of human trafficking, and asylees, can still purchase Marketplace coverage but will no longer be eligible for premium tax credits. Without subsidies, many may be unable to afford their premiums and could drop coverage. CBO estimates that one million more individuals will be uninsured as a result of this provision by 2035.
7. Enrollees will face the elimination of repayment limits.
Beginning in the 2026 tax year, limits that previously capped how much some Marketplace enrollees had to repay in excess premium tax credits were eliminated as enacted through the budget reconciliation law (“The One Big Beautiful Bill Act”). Because the first tax filings under the new rules will not happen until early 2027, enrollees will choose 2027 plans without having seen how uncapped repayment works in practice. Those whose incomes end up higher than projected may face larger tax bills than they expect, and accurately estimating income and updating it when circumstances change will be especially important for people near income thresholds for premium tax credits or cost-sharing reductions.
Some enrollees may be able to lower their modified adjusted gross income (MAGI) through contributions to accounts such as health savings accounts (HSAs) or traditional individual retirement accounts (IRAs). These contributions could increase premium tax credits or help people near 250% FPL qualify for cost-sharing reductions (CSRs). However, HSA contributions are available only to people enrolled in HSA-eligible plans, and not everyone has the funds to contribute. Because Marketplace assistance is based on projected annual income, enrollees considering this approach may also need to update their income estimates during the year.
8. Consumers who are denied or removed from Medicaid coverage for not meeting work requirements will also be ineligible for premium tax credits.
Starting in 2027, in states required to implement Medicaid work requirements, consumers who lose or are denied Medicaid coverage solely for not meeting work requirements will also be ineligible for subsidized Marketplace plans in these states. Prior to the budget reconciliation law, a consumer who was denied Medicaid coverage or disenrolled from Medicaid could sign up for Marketplace coverage as long as they met Marketplace eligibility requirements. Because income eligibility for Medicaid references a monthly income whereas Marketplace premium tax credits are based on an estimated annual income, consumers may be concurrently eligible for both, especially in Medicaid expansion states. While this is likely a small group of people, it may include individuals who recently lost a job and who would likely not meet the Medicaid work requirements.
When the budget reconciliation law was signed, only Georgia had Medicaid work requirements in place; the law now requires 43 states and the District of Columbia to implement work requirements by the start of 2027. Exclusion from ACA tax credits based on failing Medicaid work requirements will apply to adults in Medicaid expansion states and those that are covered under Medicaid Section 1115 waiver programs to expand coverage. People who lose Medicaid coverage as a result of these requirements, including those who are working or qualify for an exemption but fail to navigate reporting rules, may face challenges finding affordable coverage because they will remain ineligible for premium tax credits until they are no longer eligible for Medicaid for reasons other than not meeting work requirements (such as a change in income).
9. Litigation has halted implementation of some Marketplace requirements for 2027.
Litigation challenging two final regulations that make substantial changes to Marketplace requirements – the 2025 program integrity rule and the HHS Notice of Benefit and Payment Parameters for 2027 – have halted implementation of many new rules for the time being. Four key cases are working their way through the courts: The 2025 program integrity rule was challenged in City of Columbus et al. v. Kennedy (Columbus I) and California et al. v. Kennedy (California I). Litigation over the 2027 Payment Notice is also ongoing in City of Columbus et al. v. Kennedy (Columbus II) and California et al. v. Kennedy (California II), with some provisions of the 2027 Payment Notice stayed as the litigation continues.
The state of play after several court decisions over the past year include the following:
- Failure to reconcile requirement: For plan year 2027, consumers will not be disqualified from receiving premium tax credits if they fail to file and reconcile prior years’ premium tax credits. So, for example, an enrollee who failed to file their tax return and reconcile for the 2025 tax year in 2026, will not lose subsidies for 2027 coverage.
- Expansion of eligibility for catastrophic plans: A 2025 announcement expanded who can enroll in catastrophic plans, allowing individuals who were not eligible for premium tax credits or other cost-sharing help because their projected income was below the federal poverty level or above 250% FPL to sign up for catastrophic coverage. This expanded eligibility has been temporarily paused due to a June decision in Columbus II. This means only a narrow group of people including individuals under age 30, those whose Marketplace or employer coverage would cost more than 8.5% of their income, and those who qualify for a hardship exemption can enroll in these plans during open enrollment.
- Other requirements are not in place for now or have been vacated. Due to litigation, CMS has stated that it will not implement a long list of final requirements. This includes certain income verification requirements, network adequacy requirements, and the elimination of standardized health plans. In addition, other requirements, including an Administration rule that would prohibit states from including gender-affirming care as an essential health benefit and a rule that would have shortened the Open Enrollment Period to nine weeks, have been vacated.